Funding arb limits to account for
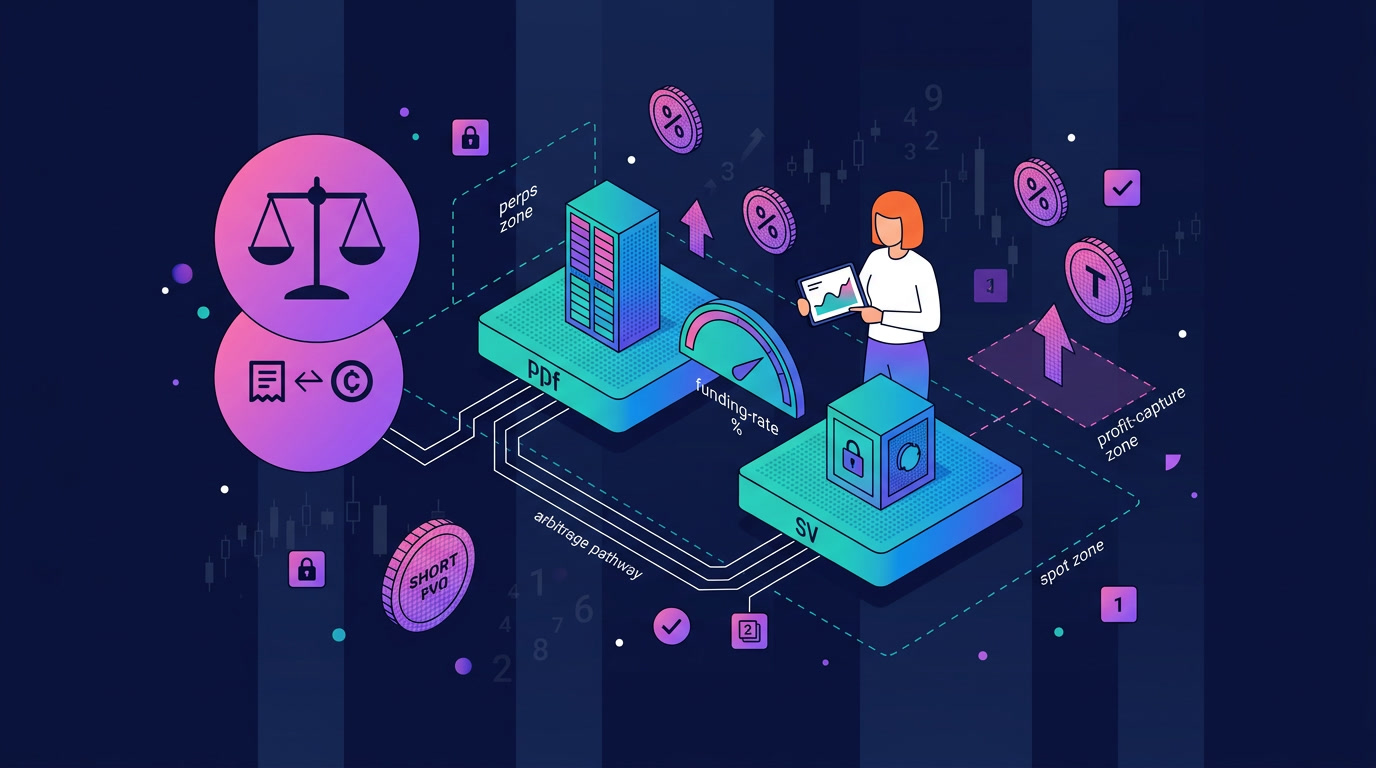
Funding rate arbitrage is a delta-neutral strategy that captures the periodic funding payment exchanged between long and short traders on perpetual swap contracts Sharpe AI. The core mechanic relies on maintaining offsetting positions to isolate the yield, but several structural constraints limit its practical application in 2026.
First, the strategy requires significant capital efficiency. Since you must hold both long and short positions, your usable capital is effectively halved compared to a directional trade. This double exposure increases the operational overhead of managing two separate legs of the trade.
Second, funding rates are not static. They fluctuate based on market sentiment, liquidity depth, and exchange-specific mechanics. A rate that appears profitable at entry can compress or flip negative before the next payment interval, eroding your margin. This volatility demands constant monitoring and rapid execution.
Finally, exchange risk and withdrawal limits pose a silent threat. If an exchange experiences liquidity issues or suspends withdrawals, your locked collateral may become inaccessible. Diversifying across multiple reputable platforms mitigates this, but it fragments your capital and complicates rebalancing.
Funding arb choices that change the plan
Funding rate arbitrage promises delta-neutral yield, but the strategy is rarely free. The gap between spot and perpetual futures prices reflects real market sentiment, and exploiting that gap requires managing several moving parts. Before deploying capital, you need to understand where the yield comes from and where the hidden risks live.
The primary tradeoff is between yield stability and execution complexity. Positive funding rates usually signal bullish sentiment, meaning shorts get paid by longs. However, this environment often correlates with rising asset prices, which introduces basis risk if the premium collapses. Conversely, negative funding environments offer cheaper entry but require you to pay the funding rate, turning the trade into a cost rather than an income stream.
Beyond market direction, operational costs and counterparty risk define the real bottom line. Exchange fees, withdrawal limits, and slippage can erode thin margins. Relying on a single exchange introduces counterparty risk; a platform outage or freeze can lock up capital during volatile periods. Diversifying across venues mitigates this but increases management overhead.
To evaluate whether a specific funding arb setup is viable, compare the key variables side-by-side. The table below breaks down the core factors that determine net profitability and risk exposure.
| Factor | Impact on Yield | Risk Level | Mitigation Strategy |
|---|---|---|---|
| Funding Rate Volatility | High | Medium | Monitor historical averages; avoid chasing peak rates |
| Exchange Fees | Medium | Low | Use maker orders and fee tiers; compare spot vs. perp fees |
| Basis Risk | High | High | Keep positions delta-neutral; hedge with spot or other perps |
| Counterparty Risk | Critical | High | Diversify across multiple reputable exchanges |
| Liquidity Depth | Medium | Medium | Trade high-volume pairs; avoid low-cap alts |
| Operational Costs | Low | Low | Automate rebalancing; minimize manual interventions |
Build a Funding Arb Decision Framework
Funding rate arbitrage relies on capturing periodic payments by maintaining a delta-neutral position, but executing it profitably requires more than just spotting a high rate. You need a practical checklist to evaluate whether the spread justifies the capital lock-up and operational risk. This framework helps you filter signals from noise, ensuring you only pursue trades where the yield outweighs the costs.
1. Verify Data Accuracy and Timing
Funding rates update every eight hours on most major exchanges, but discrepancies exist between spot and perpetual prices. Use a reliable data aggregator to confirm the current rate and the time until the next settlement. Relying on a single exchange’s data can lead to mispricing, especially during high volatility. Cross-reference with a second source to ensure the spread is genuine and not a fleeting glitch.
2. Calculate Net Yield After Fees
A high funding rate is meaningless if trading fees and funding payment costs eat the profit. Subtract taker fees for opening and closing positions, plus any maker fees if you’re providing liquidity. Factor in the cost of borrowing if you’re using margin. Only proceed if the net annualized yield is at least 2-3% higher than your risk-free baseline to account for slippage and potential liquidation risks.
3. Assess Platform and Counterparty Risk
Not all exchanges offer the same security or funding rate reliability. Stick to platforms with a proven track record of transparent operations and sufficient liquidity. Avoid smaller exchanges with thin order books, as they may experience sudden rate spikes followed by immediate reversals. Check if the platform has a history of freezing withdrawals or altering funding mechanisms, which can trap your capital.
4. Monitor Liquidation Price and Margin
Delta-neutral strategies still carry risk if the price moves sharply against your leveraged position. Calculate your liquidation price with a wide buffer to avoid forced closures. Use isolated margin to contain risk to the specific trade, and maintain extra collateral to absorb temporary drawdowns. If the required margin exceeds 50% of your capital for a modest yield, the risk-adjusted return is likely poor.
Configure automated alerts for funding rates exceeding your threshold. This allows you to react quickly to market inefficiencies without constant manual monitoring. Use tools that track both spot and perpetual prices to identify divergences in real-time.
Always use limit orders to enter and exit positions. This minimizes slippage and ensures you pay maker fees where possible. Avoid market orders, which can erode your profit margin, especially during volatile market conditions when spreads widen.
Regularly rebalance your positions to maintain delta-neutrality as prices shift. Exit the trade when the funding rate drops below your target yield or if market conditions change significantly. Do not hold positions indefinitely; lock in profits while the spread is favorable.


As an Amazon Associate, we may earn from qualifying purchases.
Spotting Weak Funding Arb Options
Not every delta-neutral setup survives the spread. Many traders chase high nominal yields without checking the mechanics that actually pay out. This section highlights the specific traps and misleading claims that drain returns in 2026 funding arbitrage.
Ignoring the Basis Risk
A common mistake is assuming a high funding rate guarantees profit. If the spot-futures basis moves against your hedge, the funding payment is wiped out by capital loss. Always calculate the break-even basis change before entering.
Overlooking Exchange Counterparty Risk
Many platforms offer "zero-fee" funding arbitrage but hide costs in wide spreads or poor liquidity. If the exchange has low trading volume, you cannot exit your hedge quickly during volatility. Stick to venues with deep order books and transparent fee structures.
Chasing "Guaranteed" Yield Promises
Any strategy promising fixed, risk-free returns is misleading. Funding rates fluctuate wildly based on market sentiment. A strategy that worked last month may lose money today if the market shifts from long-biased to short-biased. Treat these yields as variable income, not fixed interest.
Funding arb: what to check next
Funding rate arbitrage is often misunderstood as a guaranteed yield, but it requires active management and strict risk controls. Below are practical answers to the most common objections before you deploy capital.
No comments yet. Be the first to share your thoughts!